Multi-market swing screener
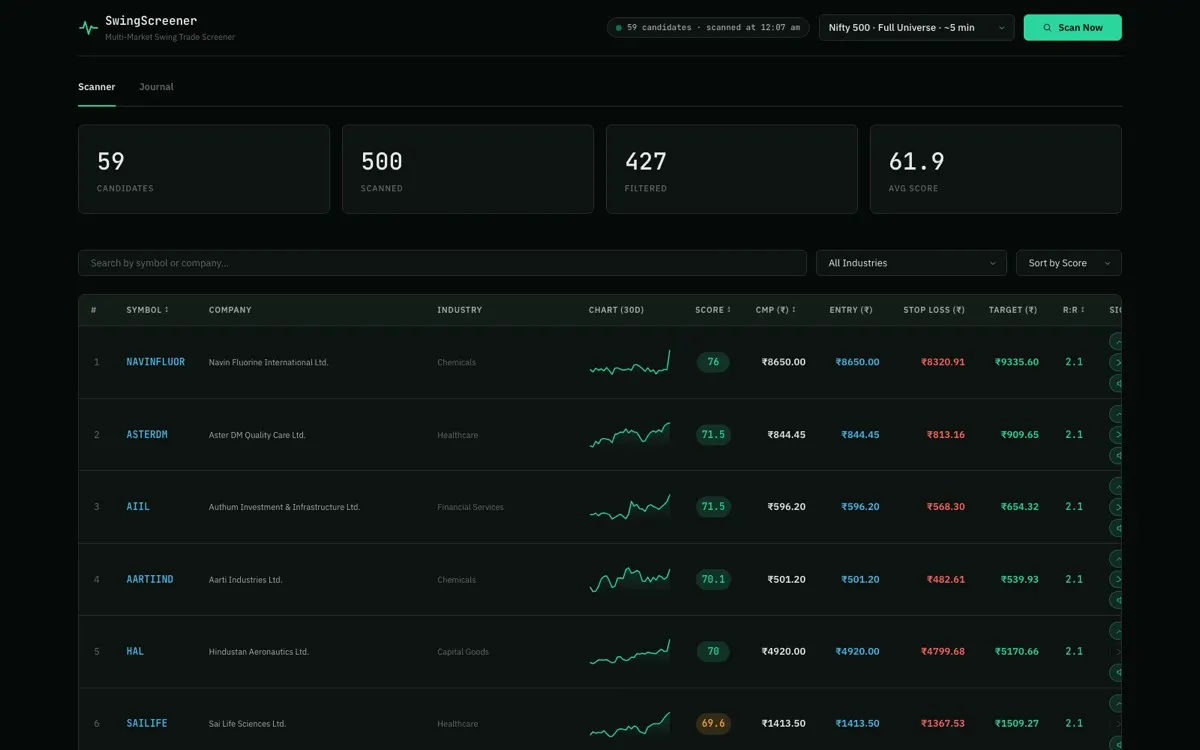
A screening engine that scans an equity universe and only lets a setup through once its stop, targets and risk to reward are defined.
Context
Most screeners stop at "this looks interesting". The hard part of a swing trade is the exit: where it is wrong, where it is right, and whether the distance between them is worth it.
The idea
Make risk part of the screen, not an afterthought. Candidates are scored by a multi-factor model, then sized with ATR-anchored stops and tiered targets, and anything below a minimum risk to reward never reaches the list.
Details
- Volatility-adjusted pricing and momentum indicators feed a probabilistic scoring matrix.
- It looks for two kinds of setup: mean reversion and trend continuation.
- Stops come from ATR, not fixed percentages, so a volatile stock gets a wider stop and a smaller position.
- A journal tab keeps the trades taken next to the scans that produced them.
What shipped
Runs as a FastAPI service on AWS (ap-south-1). A full Nifty 500 scan takes about five minutes. Try it.